
Loading article...
Slot ID: blog-post-top
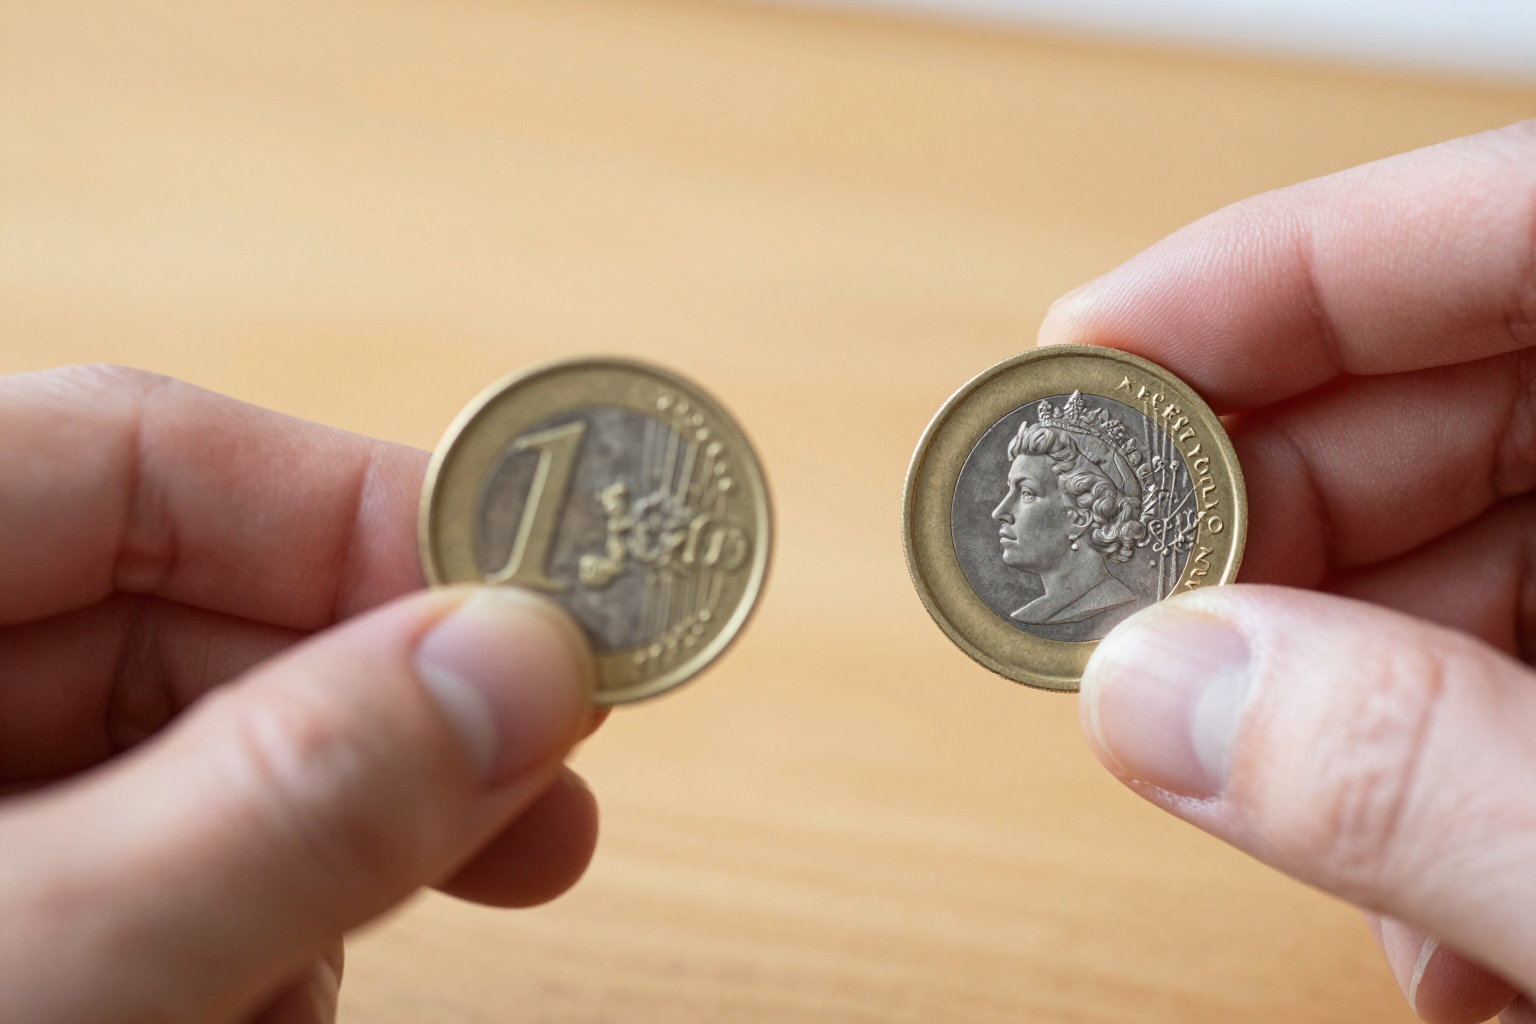
Converting euros to pounds is something many of us do without a second thought: you log into your bank, enter an amount, and hit send. But the exchange rate your bank applies is often far worse than the rate you see on Google. Over the course of a year, those hidden costs can add up to hundreds of pounds.
Take a simple example. You want to transfer €3,000 to a UK bank account. The mid-market rate is 1 EUR = 0.85 GBP. If your bank gives you 0.82 instead, you receive £2,460 instead of £2,550. That's a £90 difference for a single transfer.
The mid-market rate is the rate at which banks buy and sell currencies among themselves. It's the number you see on Google when you search for "euro to pound" or "EUR to GBP". It changes every second as currencies are traded globally.
No consumer, not even a large corporation, gets the exact mid-market rate. The rate you're quoted is always adjusted by a margin. For a quick exchange at an airport kiosk, that margin can exceed 10%. For a standard bank transfer, it's usually between 2% and 5%.
Knowing the current mid-market rate is essential because without it, you can't tell if you're getting a fair deal. Check the rate on a reliable website or with your provider before confirming any transfer.
This dynamic isn't unique to euros and pounds. The same applies in reverse. If you're converting pounds to euros, our guide to the pound to euro exchange rate explains how to avoid the same hidden fees.
Banks love to advertise "free international transfers" or "zero commission". What they don't advertise is the hidden margin they build into the exchange rate. A study by Which? found that UK banks were charging an average markup of 3.1% on foreign currency transfers. That's the difference between the rate you see online and the rate they actually give you.
Suppose you send €10,000 to a recipient in the UK. The live mid-market rate is 0.85, but the bank's rate is 0.824, a 3% margin. You receive £8,240 instead of £8,500. That's £260 going straight to the bank's bottom line.
These hidden margins affect every currency pair, not just euro to pound. For example, if you're sending money from the UK to India for family support or property purchases, you'll find the same overpricing baked into the pound to INR rate. The tips in our dedicated guide will help you recognise these charges and stop paying them.
Getting a fair rate doesn't require any special skills. It just takes a little preparation. Follow these three steps for your next transfer.
Before anything else, look up the current euro to pound mid-market rate on a free tool like XE or Google. This gives you a benchmark. When a provider quotes you a rate, you can instantly see how much worse it is than the benchmark.
Don't be swayed by a low headline rate. The total cost includes both the exchange margin and any fixed fees. Let's compare three options for a €2,000 transfer:
In this case, Provider B wins, despite charging a fee. For a smaller transfer, the equation changes. Always run the numbers with the exact amount you plan to send.
Specialist firms like Wise, CurrencyFair, and Revolut operate differently from banks. They use the real mid-market rate and charge a transparent fee on top. Their fees are almost always lower than the total cost of a bank transfer, especially for larger amounts.
These services aren't just for euro-pound conversions. If you're sending euros to India, the same principles apply. Our article on the euro to INR exchange rate explains how to get the real rate and avoid the overpayment traps that catch many expats and businesses.
Exchange rates rarely stay still. The euro to pound rate can move by half a percentage point in a single week. If you're not in a rush, you can use that volatility to your advantage.
Set up a rate alert on XE or with your transfer provider. You'll get notified when the rate reaches your target. You can also set a limit order: tell your provider you want to convert when the rate hits, for example, 0.86. When it does, the transfer goes through automatically. This is a practical way to lock in a good outcome without constantly watching the market.
One caveat: currency markets are impossible to predict with certainty. Don't set an unrealistic target and wait forever. Use recent rate history to choose a level that's actually achievable.
The larger the transfer, the more every decimal point matters. On €100,000, a 1% difference works out to €1,000. So it's worth shopping around for custom quotes, and many providers will beat their standard rate for high-value transfers if you ask.
If you're buying property in the UK or paying tuition, consider a forward contract. This lets you lock in the current euro to pound rate for a transfer that will happen later. You might lose out if the rate improves, but you gain certainty, which is often more valuable. For example, if a home purchase completes in three months, locking in today's rate can protect you from a surprise drop.
These strategies are universal. Anyone moving money between different currencies can apply them. If you're dealing with Australian dollars and Indian rupees, for instance, check out our guide to the AUD to INR exchange rate. It covers the same cost-saving tactics and shows you how to keep more money on every transfer.
Slot ID: blog-post-bottom