
Loading article...
Slot ID: blog-post-top
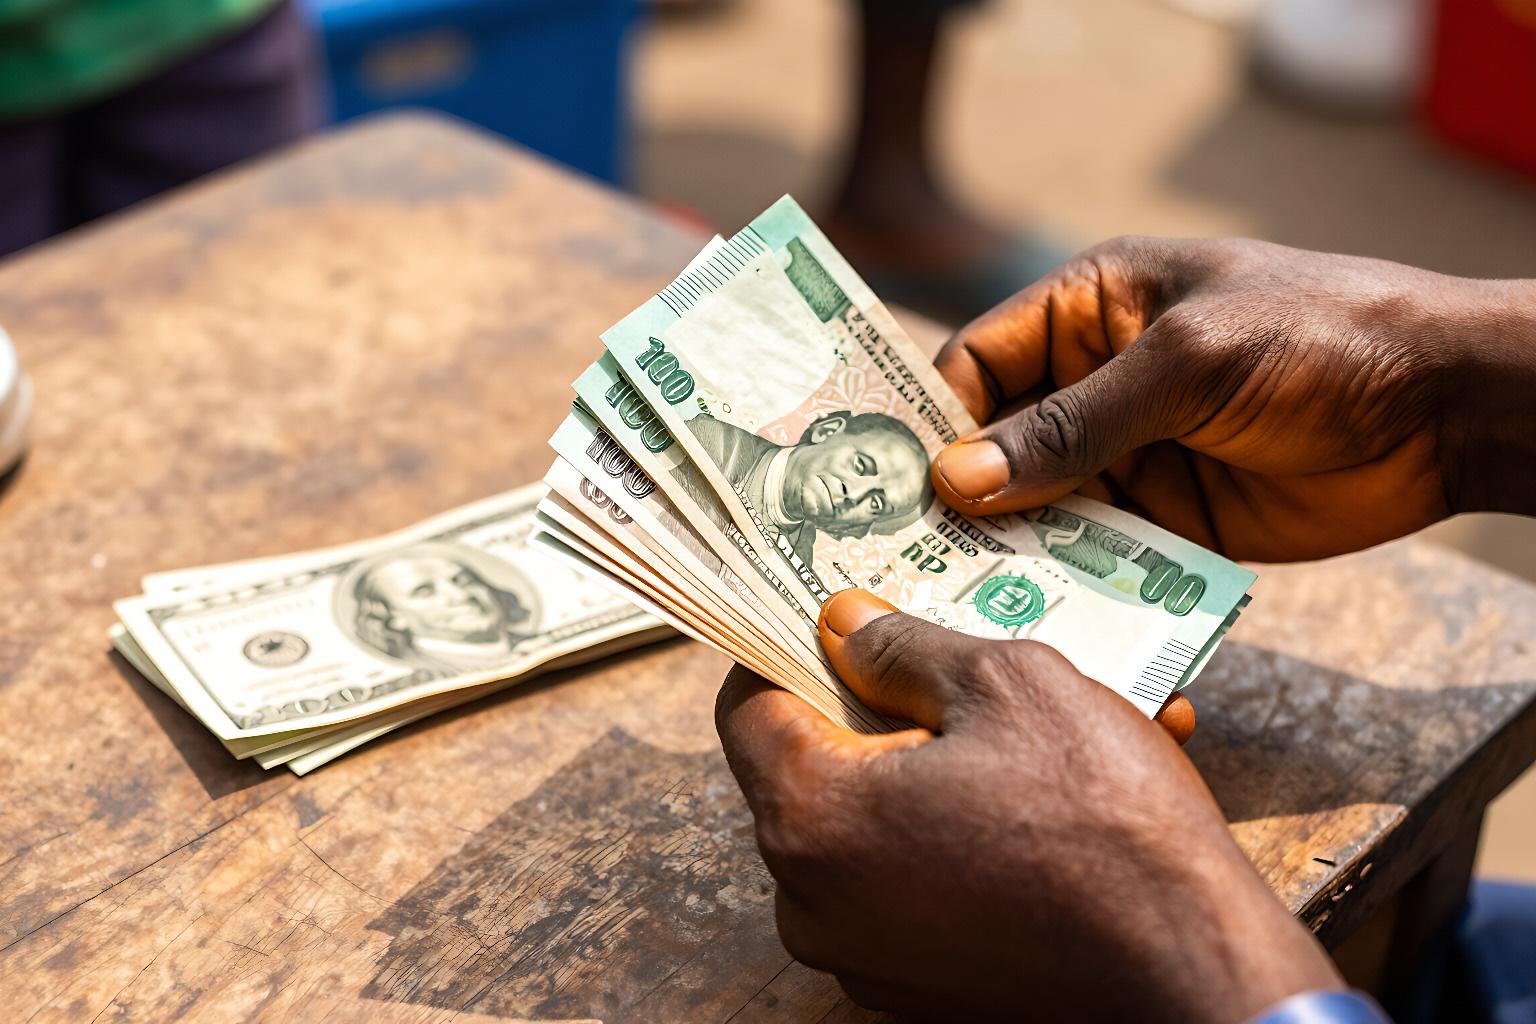
You have ₦2,400,000 in a Nigerian account and school fees are due in dollars next week. Or a client in London owes you $3,000 and you want to know what that lands as in naira. Either way you open a converter, type in the number, and get a figure. That figure is almost never what you actually end up with.
Converting NGN to USD is not complicated. Getting a fair deal on it takes a bit of attention, mostly because the naira does not have one exchange rate. It has several, they move independently, and on the same afternoon they can differ by 20% or more.
When you convert NGN to USD, you are usually doing one of three things:
Each of those has a different cost structure, and each one quotes you a different number. Assuming they should all be the same is where people lose money.
This is the rate published through the Central Bank and used by commercial banks for documented transactions. You can access it for things like tuition, medical bills, and business imports, but supply is limited and you will need paperwork: invoices, admission letters, forms, sometimes a waiting list. The official rate is usually the cheapest on paper and the slowest in practice.
Bureau de change operators and street dealers set this one. It moves hourly, it is faster, it needs almost no documentation, and it is usually weaker for the naira than the official rate. Dealers negotiate, and the price you get depends on the amount, the day, and how well they know you. Someone changing $200 gets a worse rate than someone changing $5,000, every time.
Google, XE, and most currency apps show a mid-market figure. It is a reference point between buyers and sellers, not an offer to anyone. No bank or dealer will sell you dollars at the mid-market number, because that is the number where nobody makes money. Treat it as a starting line, not a price. This guide to reading an NGN to USD converter properly explains why the mid-market figure misleads so many people.
Fees rarely show up as a single line item. They hide in five places:
A provider advertising "zero fees" is usually just folding the cost into a wider spread. The fee did not vanish. It moved.
Say the mid-market rate is ₦1,550 to the dollar and you need $2,000.
Dealer A quotes ₦1,610 flat, no fee. Cost: ₦3,220,000.
Dealer B quotes ₦1,585 but charges a ₦15,000 processing fee. Cost: ₦3,185,000.
Dealer C quotes ₦1,560 and sets the rate at settlement in 48 hours. If the naira slips 3% before then, you pay closer to ₦3,210,000 and get nothing back.
Dealer A looks like the worst rate on the board. Dealer B is the cheapest by ₦35,000 right now. Dealer C is a gamble dressed up as a bargain. This is why the quoted rate alone tells you almost nothing, and why the difference between the displayed rate and the rate you actually receive matters more than the headline number.
Skip the rate question. Ask how many naira leave your account and how many dollars land at the destination. Two figures, all-in. Anyone who cannot answer that clearly is either guessing or hiding something.
Rates move, so a quote from yesterday is useless. Compare a bank, a bureau de change, and a fintech app back to back. The gap between best and worst is frequently ₦20 to ₦40 per dollar, which on $2,000 is ₦40,000 to ₦80,000.
If the provider says "rate locked for 30 minutes," get it in writing, then send the naira inside that window. If they say the rate is confirmed at processing, assume there is a built-in cushion working against you.
Changing $10,000 in one go gets you a better headline rate but also draws attention, and some dealers will renegotiate mid-transaction. Two or three smaller conversions across different providers often nets a better average and reduces the damage if one goes wrong.
Nigerian banks ask questions about large dollar inflows and outflows, and so does the tax office if you are running a business. Screenshots of the rate, the transaction reference, and the receiving account details save hours of arguing later.
A lot of people searching for NGN to USD rates are actually holding dollars and buying naira, which is a different transaction with a different set of traps. The smarter approach to converting USD to NGN covers the reverse direction, and the gap between the naira figure on screen and what you receive is worth reading before you sell dollars to anyone.
Yes, more than most people expect. The parallel market reacts fast to policy announcements, FX auction results, and central bank circulars. Spreads widen on Fridays and the day before public holidays, when dealers are managing their books and demand spikes. Month-end tends to be expensive because importers are settling invoices.
The practical rule: never convert on a deadline day if you can avoid it. Give yourself a week's buffer and watch the rate for a few days before you move. Panic converting is where the worst rates get signed.
If you receive dollars regularly, whether from clients, family, or a salary, a domiciliary account lets you hold USD without touching the naira at all. Money comes in, money stays in dollars, and you skip the spread twice: once going in, once coming out.
Likewise, if you are pricing a service for an overseas client, quote in dollars and invoice in dollars. Converting naira to dollars and back again as part of a business cycle is an expensive habit that quietly eats 4-8% of your revenue every round.
Convert when you need the other currency for a real purpose. Not because a converter app made the number look interesting.
Slot ID: blog-post-bottom